

In recent years, the financial services landscape in India has witnessed a major shift, particularly in the realm of simplified lending. The rise of digital lending platforms, fueled by advancements in fintech, artificial intelligence (AI), and alternative credit scoring, has played a pivotal role in bridging the credit gap for aspiring Indian entrepreneurs. Incidentally, this transformation has also helped bridge the gender gap and drive inclusive economic growth, as more women entrepreneurs can now avail credit to start or scale up their business.
Why do Women Entrepreneurs Face a Credit Gap?
Women entrepreneurs in India have faced significant barriers in accessing credit from traditional financial institutions. Stringent documentation requirements, the need for collateral, lack of formal credit history, and gender biases have often prevented women from securing loans to start or expand their businesses. According to a report by the International Finance Corporation (IFC), there are about 15 million women-owned MSMEs in India. About 90 percent of these entrepreneurs have not availed of formal finance on their journey. Lack of financial awareness is another reason for this gap. According to the ‘Bharat Women Aspiration Index Report’ published by Tide India in 2024, 95% of surveyed women lacked awareness of government schemes that could help finance their businesses, forcing them to rely on informal lenders.
The lack of access to credit has stifled the growth potential of women-led businesses, limiting their contribution to the economy. However, the emergence of digital lending platforms is now changing the narrative. Here is how it helps women borrowers:
- Quick and Paperless Loan Processing
Traditionally, formal lending by banks needed several physical documents, multiple branch visits, and on-ground verification of business operations for risk assessment and compliance. With digital lending, NBFCs are rapidly transforming the creditor journey through paperless loan application, verification, sanction, and disbursement processes. This enables budding women entrepreneurs to apply for loans online using minimal documentation. The reduced time and effort can be invested in the business to achieve greater returns.
2. No need for collateral
Several women entrepreneurs who start without family support do not have any tangible assets to offer as collateral. Thus, they fail to secure formal credit from banks. NBFCs bridge this gap by offering collateral-free loans and start their journey.
3. AI-Driven Credit Scoring
There is a deep methodology that allows NBFCs to offer collateral-free loans. They partner with fintech companies that deploy cutting-edge technology to assess creditworthiness through alternative data. For example, using social media behaviour, transaction history, cash flow patterns, and even mobile phone usage. With the help of artificial intelligence, large datasets from these sources can be analyzed to understand the creditworthiness of a borrower. This innovative approach opens the door for women entrepreneurs who may lack a formal credit history but have strong business potential.
4. Micro and Small Ticket Loans
Many women entrepreneurs, especially in rural and semi-urban areas, need micro or small-ticket loans to fund their businesses. At times, offering such small loans does not make economic sense for banks due to high operational costs and perceived risks. Digital lenders, however, have built their business to efficiently cater to this segment.
Challenges and the Way Forward
While digital lending has made significant progress towards bridging the credit gap for women entrepreneurs, digital and financial literacy still pose a challenge. Additionally, due to these challenges, some entrepreneurs may still find it hard to avail themselves of necessary loans or become victims of predatory lending.
Also Read: How to Choose the Right Heat Exchanger for Your Manufacturing Needs?
The regulator, NBFCs, and fintech companies must work collaboratively to solve these issues through investments in financial literacy and implementation of a strong consumer protection framework. This will ensure that digital lending emerges as a force for inclusive economic growth in India.
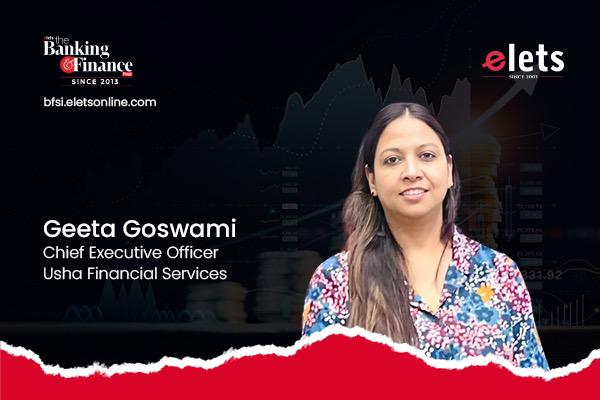
Views Expressed By: Ms. Geeta Goswami, CEO of Usha Financial Services