

Is loan consolidation a good idea? For some people it’s the cheapest money move they’ll make this year. For others it quietly adds cost.
The answer for you comes down to a few things you can check: the rates you pay now, what a new loan would charge, and how many debts you’re carrying. There’s no blanket yes or no here. This piece covers both sides honestly, with the numbers that decide it.
Loan Consolidation: Pros and Cons at a Glance
Here’s the short version before the detail.
| Pros | Cons | ||||
|---|---|---|---|---|---|
|
|
||||
|
|
||||
|
|
||||
|
|
||||
|
|
A few terms from the table. Tenure is the number of months you take to repay. A processing fee is a one-time charge the lender deducts from the loan amount. Your weighted average rate is the blended rate across all your debts, where bigger balances count for more.
Why Loan Consolidation Often Makes Sense for Credit Card Debt
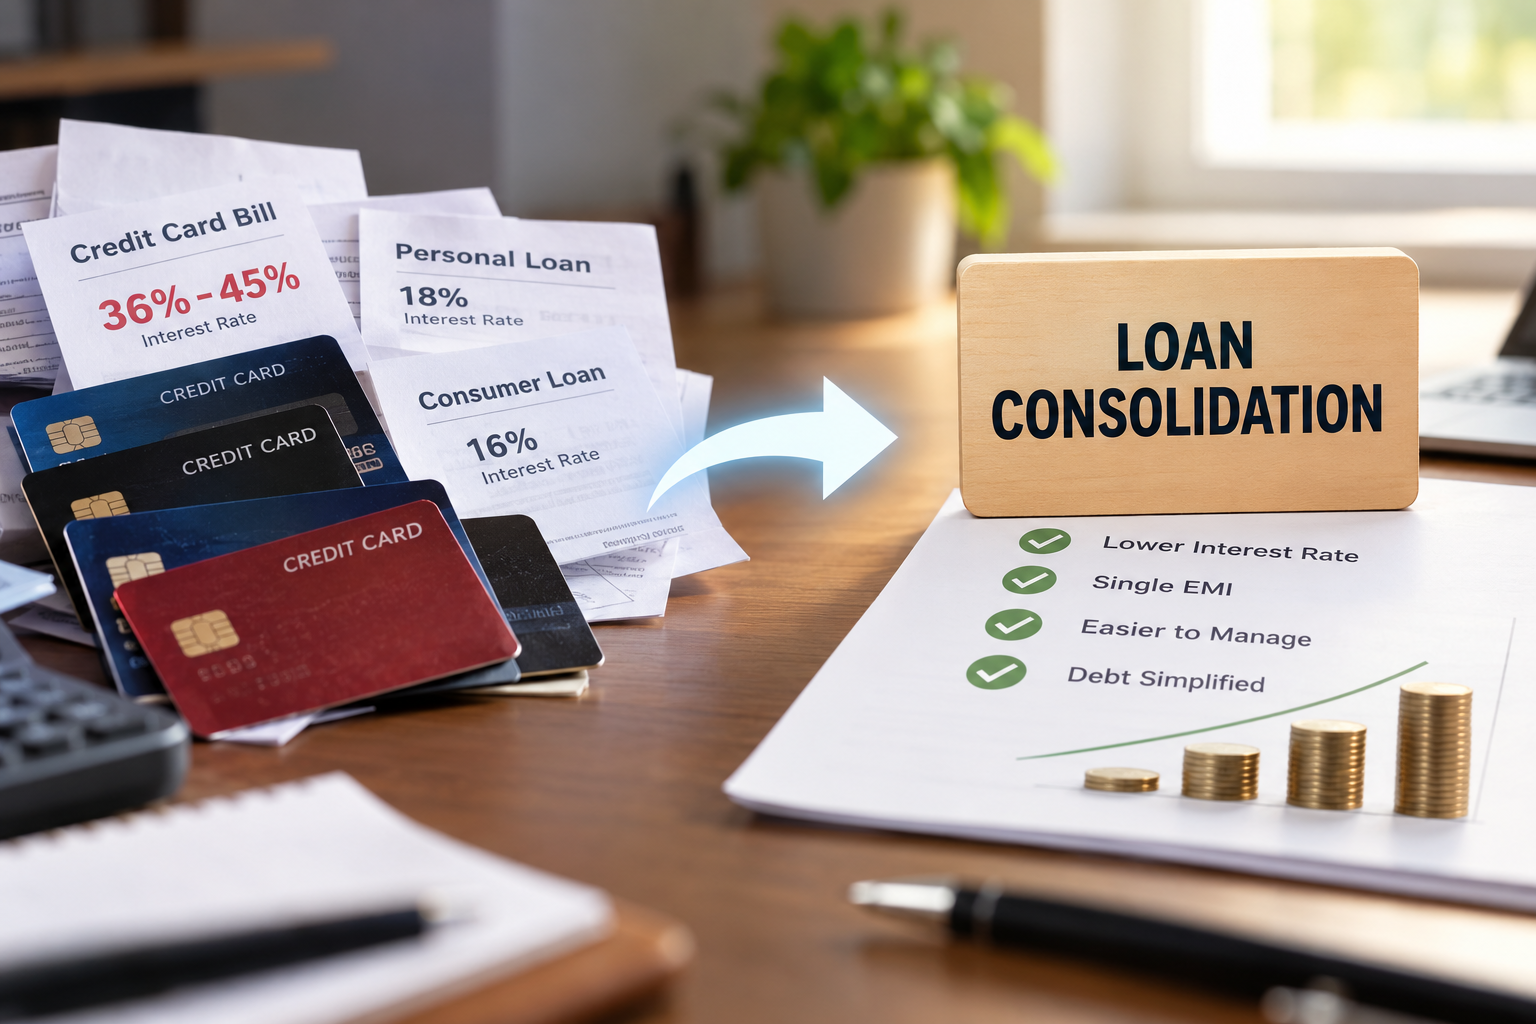
Start with the rate gap. Unpaid credit card balances in India typically carry 36% to 45% a year. A personal loan taken to consolidate usually runs between 10.5% and 24%, depending on your profile.
Few debts leave that much room. A personal loan already priced at 13% has little space to get cheaper, while a card charging 40% has plenty. And paying only the minimum due on a card sends most of each payment to interest, which is why card balances can sit almost unchanged for months.
Here’s how the loan consolidation credit card math plays out. Say ₹1.5 lakh sits across 3 cards at 36%. Left alone, that balance costs over ₹50,000 a year in interest. Move it into one loan at 14% and the yearly interest falls to well under half, then keeps dropping as each EMI brings the balance down.
Treat those figures as an illustration, not a promise. Your real saving depends on the rate you qualify for, the fees and the tenure you pick.
When Loan Consolidation Is Not a Good Idea
One loan at a fair rate is the clearest case. Consolidating it adds a hard inquiry (a lender checking your credit report) and possibly a fee, for very little gain. A balance transfer, which moves that single loan to another bank at a lower rate, usually does the job with less paperwork.
If EMIs have already been missed, a new consolidation loan is unlikely to be approved. It’s also the wrong tool for that situation, which calls for a different conversation.
Then there’s plain arithmetic. Add the processing fee, and if the new rate still isn’t clearly below your weighted average, you’re paying to swap one cost for a similar one. On a ₹2 lakh loan, a 2% fee means ₹4,000 gone upfront, so the rate gap has to be wide enough to cover that first.
Tenure needs a note too. A longer one lowers the EMI but raises total interest. A 3-year loan and a 5-year loan at the same 14% look identical on rate, yet the 5-year one costs noticeably more overall. Whether that trade makes sense depends on how tight your monthly budget is.
Who Should Consider Loan Consolidation?
So, is loan consolidation a good idea for your situation? It usually is if most of these are true:
- You’re paying 3 or more high-interest debts, especially credit cards, to different lenders.
- Every payment is on time, but keeping track is getting harder each month.
- Your CIBIL score (the 3-digit number that shows how you’ve repaid credit) is steady or rising.
- You can commit to not building fresh balances on the cards once they’re cleared.
If all four fit, Loan Consolidation deserves a serious look. You can apply to a bank or NBFC yourself, or use a platform that compares options on your behalf.
If the last point on that list feels shaky, sort it out first. A cleared card with its full limit still open is the easiest way for the same debt to come back.
How FREED Helps You Decide on Loan Consolidation
FREED is a Loan Management Company founded in Gurugram in August 2020. It has counselled 20 lakh+ borrowers and holds a 4.7/5 rating across 3,000+ Google reviews. Its Loan Consolidation Plan is for people who can still repay but want their real numbers checked before they commit.
- FREED reviews every card and loan you carry, then compares that against what a lending partner would actually offer. You see the real saving instead of assuming one.
- It matches you to a lending partner and tenure based on your EMI-to-income ratio (how much of your monthly income goes to EMIs), not a headline rate that stretches the loan longer than needed.
- If one lending partner says no, FREED tries others that suit your profile.
The final rate and loan amount come from the lending partner. FREED doesn’t charge you a fee for consolidation, and there’s no upfront cost to find out whether you’re a fit.
So, Should You Consolidate?
Consolidation pays off when the new rate is clearly lower, every high-interest debt gets covered rather than just some, and the old cards don’t fill back up. It doesn’t when only one fairly priced loan is involved, or when repayment has already become a struggle.
Want your numbers checked before deciding either way? You can start at freed.care.