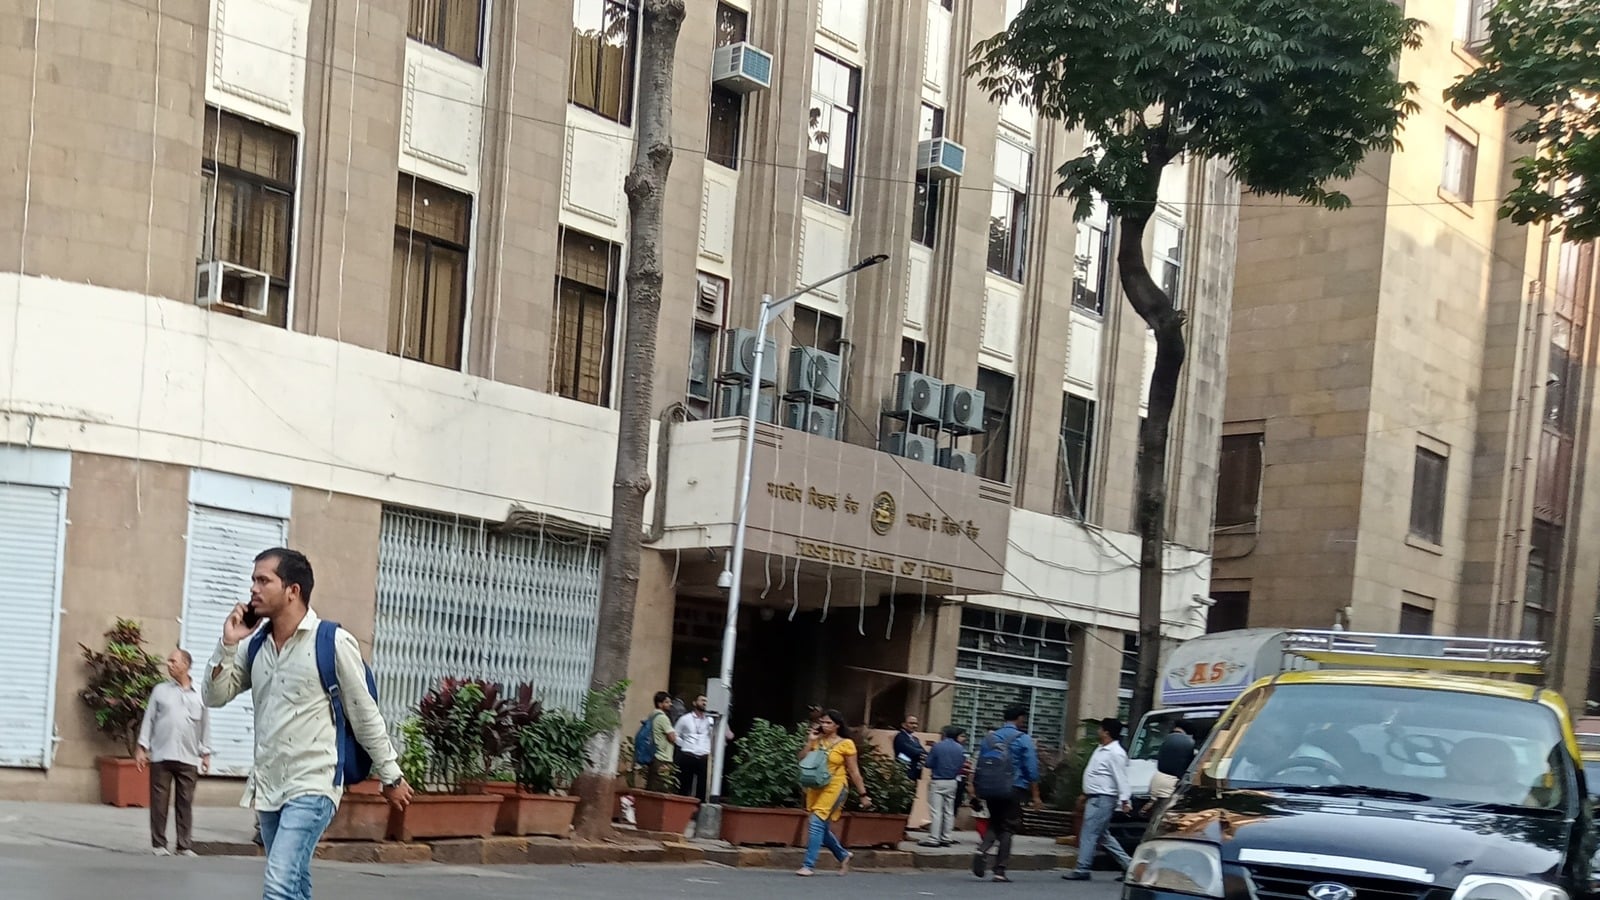


Some of India’s large banks have stepped back from a lucrative foreign exchange arbitrage trade after picking up signals that the Reserve Bank of India (RBI) is uncomfortable with it, The Economic Times reported on 27 October 2026. Lenders have either unwound buy-sell swap positions they had already built or dropped deals that were in the pipeline.
How the trade worked
The opportunity grew out of the roughly $132 billion of foreign currency non-resident (FCNR) deposits that banks mobilised from the diaspora. Banks swapped those dollars with the RBI for rupees, and the central bank took on the full cost of hedging the currency risk on the principal. That left the system with a large pool of cheap rupee liquidity.

Some banks then used that surplus to run a buy-sell swap in the interbank market, buying dollars in the spot market and selling them in the forward market. The dollars raised this way were parked in US Treasury bills, whose yields have climbed over the past three months. Because a bank that sells dollars forward earns the forward premium, the trade offered two sources of return at once.

According to bankers quoted in the report, the one-year forward premium was above 4.5% (it eased on Monday) while US Treasury bill yields were near 4.4%, taking the gross return on the trade close to 9%.
Why the regulator may object
The concern is about how the rupees are being used. Banks received those rupees by swapping FCNR dollars with the RBI, which is bearing the currency risk, so the regulator would logically prefer that the money flows into domestic lending rather than being recycled into dollar assets abroad. Three people told ET that some banks had received feelers from the RBI to that effect. The central bank did not respond to queries, and the signal has not been officially confirmed.

A senior private sector banker said the RBI is not necessarily opposed to buy-sell swaps as such. More forward selling by banks would soften forward premiums and lower hedging costs for importers. The regulator is also unlikely to object if the dollars are lent to corporates as trade finance, or deployed overseas only for very short periods.
RBI’s own swaps fed the premium
Bankers pointed out that the high forward premium that made the trade attractive was partly a by-product of the RBI’s own liquidity management. To absorb surplus rupees, the central bank ran sell-buy swaps, selling dollars in the spot market and buying them forward. Those forward purchases supported the premium, and some banks saw a chance to profit from it while managing their books.
The episode echoes 2008, when the RBI found some foreign banks using local rupee resources for similar swaps and placing the dollars with cash-strapped parent entities overseas. The regulator responded then by capping how much of a foreign bank branch’s local capital and deposits could be lent to or placed with its head office or overseas correspondents.
What it means for banks
The pullback comes as banking liquidity has tightened sharply in recent weeks, with the RBI moving from draining surplus funds to injecting money through variable rate repo auctions. For bank treasuries, the message is that FCNR-linked liquidity is expected to support credit growth at home, and that regulatory comfort will weigh as heavily as spreads when they size up arbitrage opportunities.