


Thirty is an age where you are considered as more mature, financially independent, and with more responsibilities.
The phase of the 30s is also considered to be one of the most incredible stages in one’s life, owing to the energy one puts into the things one does.
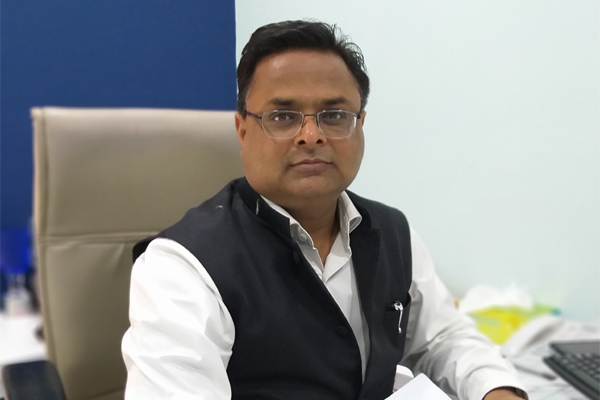
Rakesh Goyal – Director, Probus Insurance Brokers Pvt. Ltd.
In the thirties, individuals usually become financially independent. So, this is the very right time for them to think about investing in an optimum health insurance plan; as buying a policy at this age helps cover a lot of medical expenses which comes with ageing. Moreover, if there’s no pre-existing disease, buying in the early 30s gives enough time to cover up the waiting period.

Furthermore, if an individual is financially stable, then it is advisable to consider and invest in buying critical illness plan along with the health insurance plan.
Moreover, in your 30s, it is to protect yourself from loss of hard-earned savings. And, better to safeguard your future from the financial crisis that may occur due to medical emergencies. This article will help you to find some of the critical factors that one must consider while buying health insurance plan at the age of 30 years.
1) Always inform the insurer about your pre-existing diseases
While you are in your 30s, there are chances that a person is undergoing certain medical conditions or has some pre-existing disorder. Under such cases, the policy seeker needs to declare pre-existing diseases while buying the policy. Since not disclosing such information may lead to the disapproval of claim when filed. Also, some insurance companies will ask you to go through a medical checkup before issuing a policy.
In case you have a pre-existing disease, the chances are that you will be asked to pay a slightly higher premium. Although the premiums would be somewhat higher than the premium charged to someone without having any pre-existing, your claim process would be comparatively seamless and quick, which would not be the case if you hide this information. Also, for certain pre-existing disease such as diabetes, there would be few insurers who would add a waiting period.
But the best part of buying an insurance policy at your 30s in spite of pre-existing disorders is that it will offer protection against different health issues or medical emergencies in the later stage of life.
2) Your smoking habit can lead to higher premium amounts
Many insurers consider smoking is as a key deciding factor while providing a health insurance plan. The reason behind it is that smoking causes severe damages to one’s health; such a person is more prone to health problems. Individuals who smokethe chances of making a claim also increases. Due to the higher risk caused by smoking, the premiums for health insurance plans are higher for a smoker than that of a non-smoker.
3) Increase your health coverage, not a burden on your pocket
Often, the budget plays a crucial role while deciding the sum insured and the price of the health insurance plan. For higher sum insured, higher will be the amount of the premium one will have to pay.
So, how do you find the plan that has a reasonably good sum insured and fits well in your pocket? If you can’t invest now, check with your employer. These days, employers do offer health coverage to their employees and cover them under a group policy.
If you can invest a little amount every month, then it is highly advisable to go for a family floater plan. Again, by opting family floater is suitable than individual plans for each family member. To increase the coverage, you can opt for a super top-up plan.
4) Profession – Risky or Non-Risky?
The type of profession plays a primary role in deciding the cost of the premium. For example, people who work in risky environments with hazardous substances, chemicals, subject to radiations and high-risk jobs such as firefighters, armed forces, labourers,stuntmen/women etc. have to end up paying more premiums. If your profession is of a desk job, then the premium is comparatively lower.
5) Check for what are the Exclusions
There are certain medical conditions or treatments which are not covered under the health insurance plan. It is important to look for exclusions before buying a health insurance policy. These exclusionsnarrow the scope of coverage provided by the insurance agreement. Some of the common exclusions in health plans are cosmetic treatments, lifestyle-related conditions, dental, hearing, AIDS, etc. One must study the exclusions well, as it will help you to find the best fit for your needs.
One must consider these factors before buying a health insurance plan as it would affect your premiums.In addition to this, one must read the policy document thoroughly as it will help you to understand the policy better.
Views expressed in this article are the personal opinion of Rakesh Goyal – Director, Probus Insurance Brokers Pvt. Ltd.