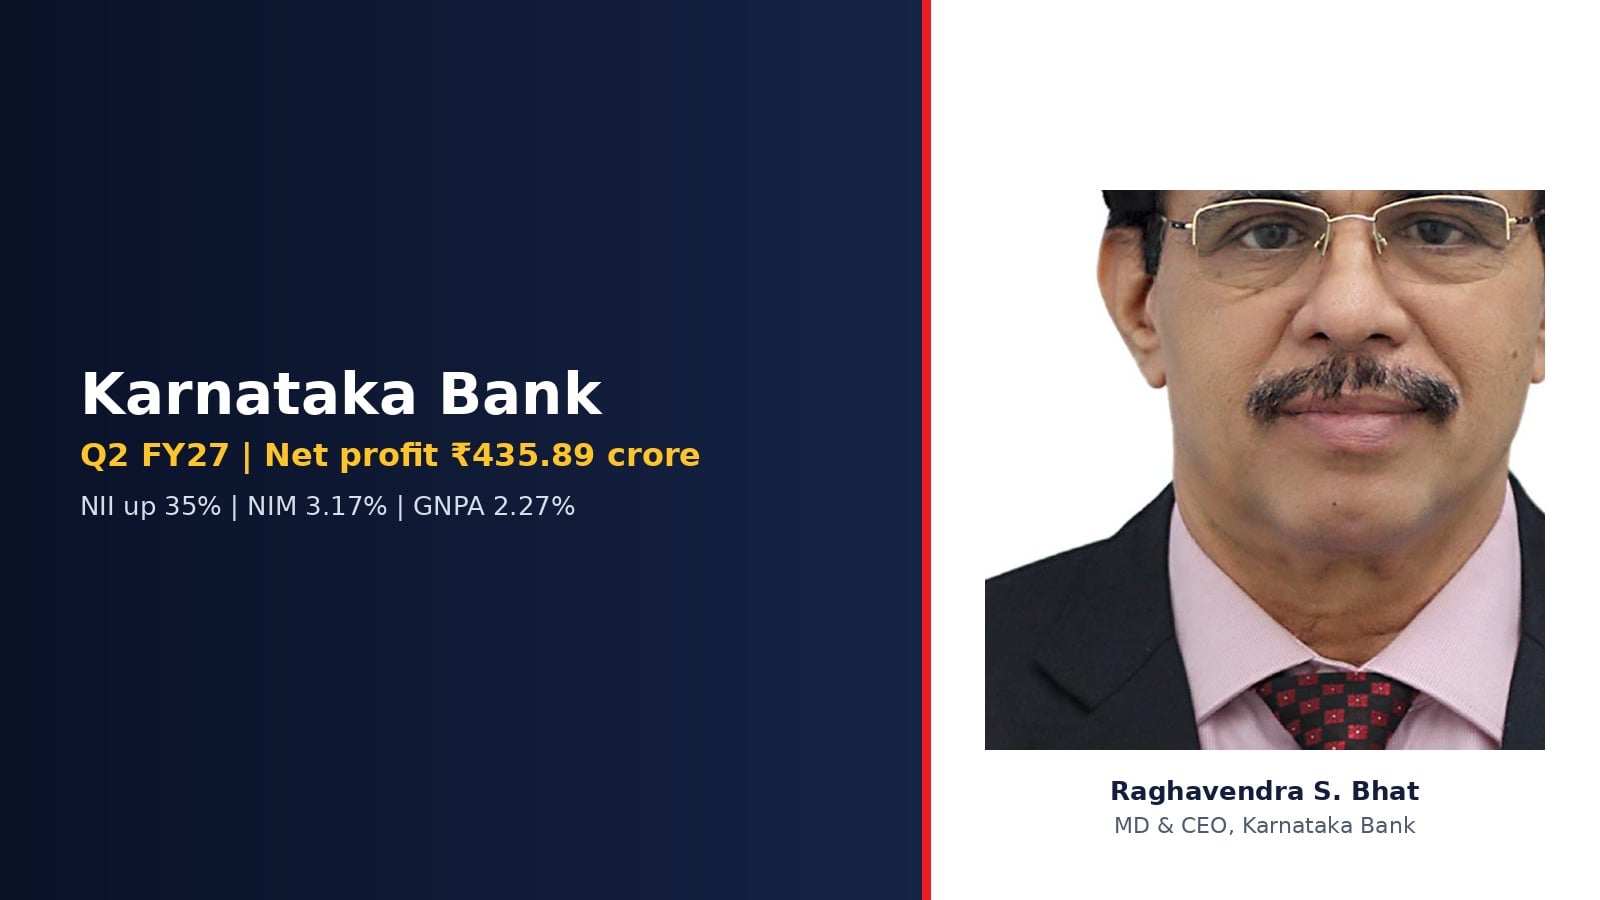


Karnataka Bank has reported a 36.6 per cent year-on-year rise in net profit to ₹435.89 crore for the second quarter of FY27, as stronger core lending income and a sharp fall in provisions lifted earnings at the Mangaluru-headquartered private sector lender. The bank had posted a net profit of ₹319.12 crore in the July–September quarter of FY26 and ₹418.95 crore in the preceding June quarter.
The results were approved by the bank’s Board of Directors at a meeting in Mangaluru on Wednesday, October 28.

Core income drives the quarter
Net interest income (NII), the difference between interest earned and interest expended, rose about 35 per cent to ₹982.44 crore in Q2 FY27 from ₹728.12 crore a year earlier. Interest earned grew to ₹2,503.87 crore, while interest expenses rose more slowly to ₹1,521.43 crore, helping the bank’s net interest margin widen to 3.17 per cent from 2.72 per cent in September 2025.

Operating profit before provisions climbed nearly 37 per cent to ₹602.22 crore. Provisions and contingencies dropped to ₹14.74 crore from ₹20.07 crore a year ago and ₹28.70 crore in the previous quarter. Total income for the quarter stood at ₹2,793.96 crore against ₹2,522.55 crore in Q2 FY26.
For the first half of FY27, net profit rose about 40 per cent to ₹854.84 crore from ₹611.52 crore in H1 FY26.

Record business, faster loan growth
Aggregate business reached a record ₹2,07,132.41 crore at the end of September. Gross advances grew 25 per cent year-on-year to ₹92,015.26 crore, outpacing deposit growth of 12 per cent to ₹1,15,117.15 crore. Retail term deposits rose 10 per cent to ₹72,197.32 crore.
“The bank has reached a historic milestone with its aggregate business climbing to a record ₹2,07,132.41 crore and net profit hitting ₹435.89 crore,” said Raghavendra S. Bhat, Managing Director and CEO, Karnataka Bank. He added that the retail, agriculture and MSME (RAM) segment expanded 19 per cent year-on-year to ₹56,968.79 crore from ₹47,958.40 crore.
Asset quality strengthens
Asset quality continued to improve. Gross non-performing assets fell 106 basis points year-on-year to 2.27 per cent, from 3.33 per cent in September 2025 and 2.58 per cent in June 2026. Net NPA declined 61 basis points to 0.74 per cent. Bhat attributed the improvement to disciplined underwriting, stronger recovery efforts and continuous monitoring of the credit portfolio.
The bank’s capital adequacy ratio under Basel III stood at a comfortable 20.36 per cent, giving it headroom to sustain its faster loan growth.
What it means
The quarter marks a clear turn in Karnataka Bank’s earnings profile: loan growth running at twice the pace of deposits has translated into a wider margin and higher core income, while near-negligible provisions point to a cleaner book. The key watch-points ahead will be whether the bank can fund its 25 per cent credit growth without pressure on deposit costs, and whether the RAM-led loan mix keeps delinquencies in check as the book expands.