

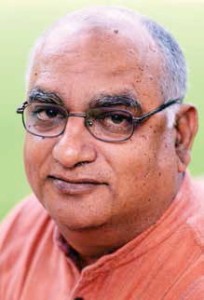
Vijay Mahajan
Chairman, Basix India
“We are the pioneer in micro credit, micro insurance, mobile based payments and use of CSCs for business correspondent services,” says Vijay Mahajan. In conversation with Nayana Singh
For more than a decade Basix has been working in the area of financial inclusion. Tell us about how you see the mission of Basix in India.
We were established in 1996, and today we are working with more than 3.5 million customers. Over 90 percent of people we are serving are the rural households and about 10 percent consist of urban slum dwellers. Our mission is to promote a large number of ways for sustainable livelihood, women and marginalised population through the provision of financial services and technical assistance in an integrated manner. BASIX strives to yield a competitive rate of return to its investors so as to be able to access mainstream capital and human resources on a continuous basis. We work in every state in the country, except Kerala and Tamil Nadu. We have extended micro-credit to over two million households and insurance to about four million individuals. Currently we have more than 6,000 outlets, which together cater to millions of customers. We are the pioneer in micro credit, micro insurance, mobile based payments and use of CSCs for business correspondent services. We take pride in the fact that we use innovative methods and technologies to promote financial inclusion. Our aim is not to dominate the segment but to keep serving the people.
There is lot of work being done to promote financial inclusion but the objectives are not being met. How do you think that this gap of service and delivery could be reduced in near future?
Right now, it seems that our focus is on extending the financial services network. All financial services require access to financial payment systems. We need to develop a system where pay-in and pay-out can be provided at a reasonable processing cost. If we compare India’s banking system with the insurance sector, then you may find a very strange phenomenon that insurance sector virtually cannot exist without agents, whereas bank prefers that all transactions must be done solely through their branches. This was the reason we recommended to install the system of business correspondent in year 2007 and it took almost four to roll out. Finally there is also a notion that anything in India which has to be done for the poor must be done in a charitable and subsidised way. It was believed that a business correspondent must be restricted to people like a retired school teacher, but ideally it should have been like retail shop or STD booth.
Is there any scope of integration of IT now and which are the areas where IT can be integrated to promote financial inclusion in the country?
Aadhaar must be integrated in the payment systems. People must be made aware about the benefits of Aadhaar. We also need to dematerialise money and the moment we do that mobile phones will start serving as bank accounts. We must not mix mobile banking with mobile money. Mobile money is the next revolution, but unless mobile money is accepted as a means of payment we will not be able to cut transaction cost. Safeguards must be installed to ensure security and safety in the systems. Once we do that we will able to achieve a lot more in implementing financial services. Mobile penetration has been increased tremendously; it is time to take advantage of this fact.
What is your vision when it comes to financial inclusion and what is the roadmap ahead?
Access to financial services is needed at the moment. People must be able to access financial services like savings in an easy manner. I am hopeful that ten years from now, mobile phones perform all the financial services without the need of bank accounts on the either side. Financial intermediation has two very important aspects: credit and savings. Mobilisation of savings/ micro savings plays a very important role in the expansion and deepening of the outreach of Financial Institutions, especially the ones engaged in rural areas, underdeveloped and under-banked areas. Savings is required as a tool for effective management of liquidity of individuals, particularly, the poor and the under-privileged, for whom savings also has a great potential for poverty alleviation. The poor would deposit their surplus funds if appropriate financial institutions and savings facilities are available.