

Personal loans are collateral-free, big-ticket loans borrowed by individuals from money-lending institutions such as banks and NBFCs. These loans are provided based on factors including a person’s level of income, credit history, repayment ability, and so on. Individuals applying for personal loans must possess a credible credit score to get them approved easily.
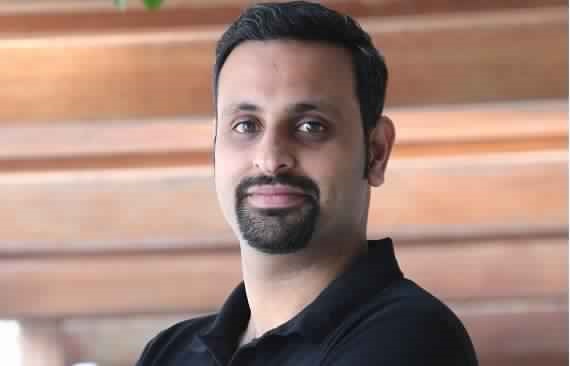
Anuj Kacker_COO & Co Founder MoneyTap
A personal loan is unsecured in the sense that it is not secured against any collateral. That is why the interest rates charged on personal loans are generally higher than those charged on home or car loans.
While this may be the case when compared with loans where large amount of money or assets put up as collateral are involved, interest chargeable on personal loans is mostly lower than those on money borrowed via credit cards. And while personal loans help you take care of unexpected expenses or any other requirement, they can also help you save money.
The following are some of the ways how:
- Lower interest rates
As discussed, interest rates charged on personal loans are lower than that charged on most credit cards. Therefore, personal loans can be used to make purchases in lieu of credit cards as a money-saving strategy.

- Consolidation of debts
You can avail a large, low-interest personal loan to pay off your other high-interest debts. By consolidating your debts like this, you can save money on a high-interest student loan or your credit card bill, for example, by repaying them faster or at once using a personal loan. However, remember to check with your bank about their prepayment policies as some money-lending institutions charge penalties for not completing the tenure of a loan or charge additional fees for foreclosing it.
- Claiming tax benefits
While personal loans do not afford you with tax benefits in general, however, if it is taken for the purpose of renovating your house or making a down payment for it, then you are eligible to claim the benefit of tax deduction of up to INR. 2 lakhs under Section 24B. In order to avail of this benefit, you will have to produce proper receipts and documents before the loan-issuing bank.
- Smart repayment plans to increase savings
Before taking a personal loan, you can choose to use the most appropriate repayment plan depending on your current and foreseeable financial status to enhance your savings. For those who are expecting their financial situation to get better in the near future, due to a promotion, for example, can apply for the step-up repayment option. This EMI scheme starts off at low interest rates that gradually increase over time.
Another option, as discussed above, is prepayment. By foreclosing your loan you can save up on interest payments. But it is important to verify beforehand whether this option will not incur a penalty.
- Improving credit score
Taking personal loans can diversify your credit type which in turn improves your credit score. And by maintaining a good credit score, you become eligible for claiming multiple benefits.
For one, your chances of getting your loans approved are enhanced and you can also get to borrow a larger amount on the back of your creditworthiness. On the money-saving front, you can leverage a good credit score to negotiate a lower interest rate on your loan or getting a waiver on processing charges, and so on.
Views expressed in this article are the personal opinion of Anuj Kacker, Coo and Co-Founder, MoneyTap