Infocomm Infocomm
24th NBFC100 TECH SUMMIT AWARDS 24th NBFC100 TECH SUMMIT AWARDS
BFSI AI SUMMIT BFSI AI SUMMIT
Home Regulators RBI SEBI TechINFRA Security Data Centre Cloud Services Government Reforms DBT Aadhaar GST Payments Payment Gateways ATM Point of Sale Payment Wallets Fintech Apps Banks Public Sector Private Sector Cooperative NBFCs Year Ender Magazine Magazine Subscription Articles Interviews Webinars Webinar Videos Video Series — Innovation Talk Upcoming Initiatives BFSI Events About Us Contact Us

RBI penalises 4 banks for non-compliance

RBI

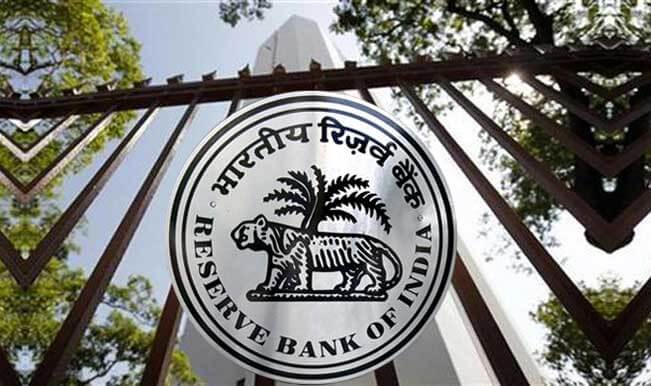
RBIThe Reserve Bank of India (RBI) has penalised four Public Sector Banks (PSBs) by imposing monetary penalty on them.

The Central bank has fined Union Bank, Dena Bank, IDBI Bank and the State Bank of India (SBI) for Rs 3 crore, Rs 2 crore, Rs 1 crore each respectively, for non-compliance with various guidelines, said the bank in its regulatory filing.
Advertisementgreylabs

While the Union Bank said that the apex bank imposed a fine of  Rs 3 crore on the bank for its delay in adherence to its directives on ‘Time bound implementation and strengthening of SWIFT related controls’ mentioned in the RBI circular of February 20, 2018.

In a filing at the Bombay Stock Exchange (BSE), Dena Bank said that RBI has imposed a penalty of Rs 2 crore for its non-compliance on the directions issued on February 20, 2018.
Advertisement24th Elets NBFC100 Tech Summit & Awards, Mumbai

The IDBI Bank, in another filing said that the regulator penalised the bank of Rs 1 crore for contravention of its regulatory directions on time-bound implementation and strengthening of operational controls pertaining to SWIFT.

“The Bank has put in place necessary corrective actions to strengthen its internal control mechanisms so as to ensure that such incidents do not recur,” IDBI said.
AdvertisementElets BFSI AI Summit & Awards, Mumbai

The SBI is imposed with Rs 1 crore penalty for late implementation of the daily settlement of Swift transaction logs with effect from February 20, 2018 at 226 “low intensity branches” of the bank.
Elets The Banking and Finance Post Magazine has carved out a niche for itself in the crowded market with exclusive & unique content. Get in-depth insights on trend-setting innovations & transformation in the BFSI sector. Best offers for Print + Digital issues! Subscribe here➔ www.eletsonline.com/subscription/

Get a chance to meet the Who's who of the Banking & Finance industry. Join Us for Upcoming Events and explore business opportunities. Like us on Facebook, connect with us on LinkedIn and follow us on Twitter, Instagram.

Our Coverage of News

TBX Launches B2B Bill Payments on TrustHub Through Bharat Connect for Business

Mumbai, September 22, 2026: TBX, formerly known as TransBnk, has launched its B2B Bill Payments capability on TrustHub… Read more →

Yugal Tiwari Appointed Chief Product and Marketing Officer at BharatPe

Fintech company BharatPe has appointed Yugal Tiwari as its Chief Product and Marketing Officer (CPMO), bringing extensive experience… Read more →

Abhinav Trivedi Appointed MD & CEO of Standard Chartered Capital Limited

Abhinav Trivedi has been appointed as the Managing Director (MD) & Chief Executive Officer (CEO) of Standard Chartered… Read more →

‘Digital Arrests’ Fall 67%, Investment Fraud Emerges as Growing Cybercrime Threat

Mumbai, September 17, 2026: Cybercrime patterns are rapidly evolving, with so-called ‘digital arrest’ scams declining by 67 per… Read more →

State Bank of India Digitises Savings-to-Salary Journey for Existing Customers

State Bank of India (SBI) has launched a digital Savings Account to Salary Account journey in collaboration with… Read more →

novio Partners with Indian Overseas Bank to Launch Co-branded RuPay Credit Card

novio, the consumer credit platform from Credilio Financial Technologies, has announced a strategic partnership with Indian Overseas Bank… Read more →