

India’s financial technology sector has developed from a point of disruption to being an integral building block of its financial system. As evidenced by the Reserve Bank of India, the Unified Payment Interface is now responsible for 85% of all retail digital payment transactions by volume. Digital lending has exploded in recent years, and projections suggest that it will exceed USD 720 billion by 2030. The question is no longer if the scale of lending has increased, but rather whether this new lending scale will facilitate financial inclusion responsibly or contribute to an increase in systemic risk.
The inclusion breakthrough powered by data
Fintech has the potential to provide services to populations that have historically lacked access to formal financial services. Traditionally, lenders were unable to appropriately assess creditworthiness for thin-file or new-to-credit borrowers. However, lenders are now using artificial intelligence (AI) driven systems to assess creditworthiness based on alternative data such as GST filings, telecom usage patterns, and transaction histories.
Built on public digital infrastructure like Aadhaar, UPI, and Account Aggregators, this model has made financial inclusion commercially viable. Digital lending has brought a sea change in how MSMEs and individuals outside metro cities access credit, according to NITI Aayog’s report “Enhancing MSMEs Competitiveness in India” in collaboration with the Institute for Competitiveness (IFC). This expansion signals a structural shift in how credit is delivered and consumed.
Yet, inclusion creates new vulnerabilities when it operates without protective measures. The process of onboarding customers, together with instant loan disbursement, creates a risk of excessive borrowing among first-time borrowers with limited financial literacy.
Regulation is now a structural force
The evolution of regulation across the Indian FinTech sector began with reactive compliance oversight and has now shifted to a proactive design. The Reserve Bank of India’s Digital Lending Guidelines require banks to use Key Fact Statements along with mandatory cooling-off periods and direct disbursal to borrower accounts. These measures aim to improve transparency and reduce mis-selling.
At the same time, the Digital Personal Data Protection Act has set new standards of the collection and processing of user data. Consent has transformed from a basic requirement into a legal duty. SEBI has established stricter norms for algorithmic accountability that require all automated decision-making systems to maintain audit trails.
This shift indicates that compliance is no longer a periodic checkpoint. It is becoming embedded into the operating fabric of fintech businesses.
Defining responsible innovation in practice
Responsible fintech innovation extends beyond theoretical concepts and involves a set of operational choices that determine long-term sustainable practices. The role of explainable AI is paramount to this evolution. Credit decisions must be interpretable and defensible. A model design lacking the ability to explain its outputs poses dual threats to regulatory compliance and system reputation.
Compliance needs to move upstream. Embedding regulatory checks within the credit engine ensures that governance is proactive rather than reactive. The process of risk monitoring also requires the implementation of adaptive monitoring systems. Economic fluctuations cause changes in borrower behaviour patterns. The use of static models leads to mispricing risk and exposes lenders to losses.
Designing for inclusion requires more than access. Products must account for varying levels of financial literacy. Clear disclosures, intuitive interfaces, and responsible collection practices become essential.
However, the need for human oversight continues in the decision-making process. Edge cases, grievance redressal, and collections require judgment that automated systems cannot fully replicate.
Trust as the real differentiator
In financial services, trust is the product. Growth driven purely by speed can be fragile. Speed-driven growth may be short-lived. Investors and regulators are becoming stricter in evaluating fintech companies for their governance and risk management practices.
A report by the Bank for International Settlements states that the increased reliance on technology within finance can also bring about new vulnerabilities and amplify already existing ones because of poor governance, transparency, and risk controls.
A more measured path forward
The fintech industry in India has reached a critical crossroads. With the right infrastructure in place and significant user adoption occurring, the principal concern now is to keep pace with innovation while simultaneously maintaining sufficient levels of users’ safety.
Responsible innovation is not a constraint on growth. It is what makes growth durable. In a system that is as fast and interconnected as fintech, responsibility cannot remain an afterthought. It must be built into every decision, every model, and every customer interaction.
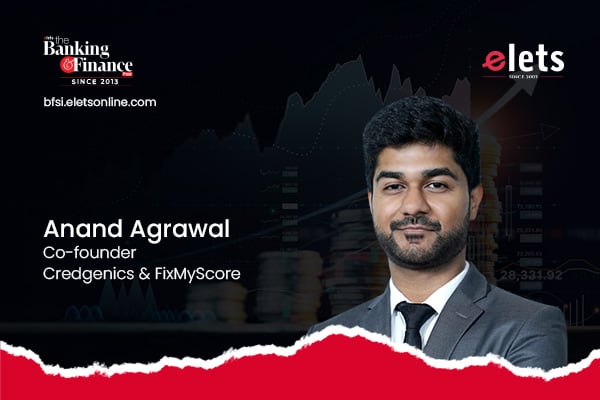
Views expressed by Anand Agrawal, Co-founder, Credgenics & FixMyScore