

The Reserve Bank of India recently put out the framework for co-origination of loans in the priority sector by banks and NBFCs. The RBI implemented the co-origination scheme in response to the liquidity problem at NBFCs in order to increase credit flow to productive sectors. The policy emphasis is on long-term structural reforms rather than short-term incentives.
Co-lending occurs when two lending institutions collaborate to make loans. The organisation enables enterprises to find consumers, conduct credit checks, and disburse a portion of the loan amount. At the same time, the agreement allows a bank to lend more money. Fintech firms are lending alongside banks in specialised categories, with an increased emphasis on offering services such as risk assessment to banks.

Bank loan syndication for large company loans has always occurred. The major problem is in the small and medium-sized firm (SMEs) industry, which accounts for a sizable portion of India’s digital financing landscape. This market is expected to be worth $300-400 billion by 2025, according to conservative estimates.

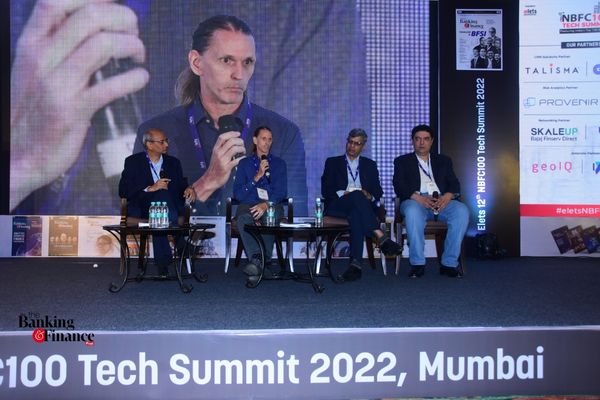
Sanjay Sharma, Co-Founder & Managing Director, Aye Finance, at a panel discussion at Elets 12th 100Tech Summit, stated that, “If we have to become a $5 trillion economy, it cannot happen unless there is enough credit access, and credit access is given to the segments that are deprived of the adequate access to credit today. Over the years NBFCs have played a complementary role to banks in reaching out to the excluded or fewer service segments. Co-lending is one of the exigencies that was created during covid by RBI. The RBI wanted a quick flow of funds to the priority sector and the excluded segment of the country.”
Other panelist of the discussion also shared their viewed on the transformation of the unmet credit gaps in the Indian economy.

Dheeraj Mittal, Chief Operating Officer, Hiranandani Financial Services, said that ” Co-lending is the way forward nowadays. Every transaction in banks and NBFCs has originated a new concept, as technology is getting emergent. For NBFCs, co-lending is a new model, and to move into a bigger market and penetrate their customers. We have seen a lot of tie-ups and engagements with banks and NBFCs, but on the ground very few transactions are getting booked under the balance sheet.”
Nirav Choksi, Co-Founder & CEO, CredAble, said that, “Almost 98 per cent of the loans we disperse are through bank’s balance sheets. Banks are being pro active and are partnering with new-age lenders. Co-lending is still slightly far away in the future, primarily because of the way banks look at exposing their balance sheet. Mindset change is still required at the level of banks and financial institutions. Larger NBFCs have traditionally operating as quasi banks, and so this is an issue across the board and not just limited to banks.
Co-lending: A Step Back:
MSMEs are critical to India’s socioeconomic development. According to the Ministry of MSME, India has over 7.9 million MSMEs, which contribute for approximately 29 per cent of the GDP. However, with the pandemic reducing global trade and domestic trade, the sector was one of the hardest hit by the capital constraint, banks’ high-risk assessment, and all-time high inflation rates. As a result, over 65% of MSMEs were temporarily closed down for three or more months in FY21, and more than half of the enterprises had a 25 per cent drop in revenue. These circumstances demonstrated that MSMEs required assistance in surviving the impact.
Why is co-lending used?
The priority sector has accepted economic hardship as a result of the pandemic and its consequences. According to industry analysts, the revitalised co-lending model has the potential to fundamentally revolutionise the sector. For one thing, banks can benefit from NBFCs’ market reach, loan origination, and servicing expertise, while NBFCs can benefit from increased liquidity and profitability.
Furthermore, according to the RBI circular, NBFCs are the sole point of contact for customers. They are in charge of loan creation, fund channelling, servicing, and collection. NBFCs have established themselves as being more effective than banks in handling loan recovery/collection due to their vast reach at the grassroots level, greater last mile connectivity, and customer relationships. As a result, this technique is intended to supplement borrowers’ prompt loan servicing.