
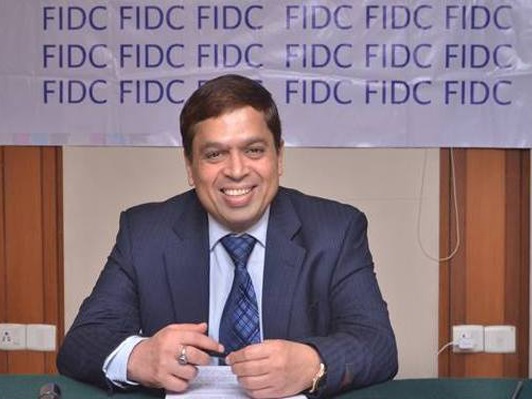


The Non-Banking Financing Companies (NBFCs) cater to the financial requirements of the MSME sector which significantly holds a prime place in supporting the Indian economy then why are NBFCs facing several challenges such as liquidity crunch and suspicion of insolvency. In a recent conversation with Elets News Network(ENN), Raman Aggarwal, Co-Chairman, Finance Industry Development Council (FIDC) speaks at length on the stimulus announced by the Centre, bottlenecks and lending objections from the banks.
Excepts of his address
On the basis of my 29 years of experience with Non-Banking Financial Companies, I truly consider NBFCs as the Iron Men of Financial services sector. I say this because of certain facts. The sector has seen some real challenging times and succeeded in coming out of the situation. At the time of every crisis, the solvency of NBFCs are questioned but that never stopped stop the sector from working and hard and serving the people. In 2018 when the IL&FS incident happened, several media reports encircling the NBFCs published some strange data quoting major liabilities. But the industry proved them to be untrue. We have always come out stronger.

Every sector has defaults and wrongdoings. In the financial domain, even the banking sector has defaults. And, during that crisis, the centre supported them to get over the situation as the banking sector is the backbone of Indian economy.
So, instead of questioning the solvency of NBFCs to meet liabilities what is better required to dive deep and look at the concerns and find out why these challenges happen, offcourse Covid is a different challenge. But there are challenges, even during the pandemic times, are peculiar to the NBFCs.
Being financial intermediaries, we borrow money and we lend money and the interest spread is our profit.
Let me also put to rest to all such debates which I totally disagree with that NBFCs are subject to light-touch regulations. This is a total myth and misnomer because NBFCs today are almost regulated at par with banks especially if you look at the asset side of the balance sheet and all key parameters are fully regulated. So it is wrong to say that the NBFCs are subject to light-touch regulations.
Also Read: FIDC writes to FinMin, requests a refinancing body for Small NBFCs
Since NBFCs are financial intermediaries, the liquidity crunch has been a major challenge especially for Small and Medium NBFCs. If you look at the sector today out of 7,000 NBFCs more than 70 percent are small and medium.
After the IL&FS discrepancy, a major liquidity crunch hit the NBFC sector. In this crisis situation, the ministry of finance and the Reserve Bank of India (RBI) both came out in support of NBFCs. Lots of steps were announced such as TLTRO 1 and TLRO 2, core generation, partial credit guarantee scheme 2.0, Atma Nirbhar package and several other. So that efforts have been made and we must give due credit because that is where it is clear that both the ministry of finance and the RBI clearly recognizes the role of NBFCs especially when it comes to funding the unfunded i.e the MSME sector. Which is also a pivotal part of the economy and which needs due support.
These initiatives definitely brought some help to the NBFCs but it was only limited to the large NBFCs that were high rated because all the announcement had three bottlenecks- mode of lending to the NBFCs-All the schemes were targeted to bank funding by investing in the bonds issued by the NBFCs. Smaller NBFCs do not access capital markets because of the complexities in the SEBI regulation, so they don’t issue any bonds. For them, the mode of borrowing is term loans. As a matter of fact, term loans were not included in the scheme of things and it simply ruled out the funding changes for smaller and medium NBFCs.
The second challenge was tenure. All the schemes provided funding for a very short period such as 3 months to 19 months. However, the funds were needed to atleast three years so that the fresh lending can be generated.
The third bottleneck was the minimum prescribed credit rating as eligibility criteria. As we know that the credit rating scale used by the rating agencies is same irrespective of the asset size of the institution. In these circumstances, getting the desired rating became a major challenge for smaller NBFCs.
The Monetary Policy statement and the statement on developmental and regulatory policies dated October 9, 2020 took some steps to boost the Indian economy.
For the first time, RBI announced an “on-tap” TLTRO facility. This should enable banks to lend more to the deserving sectors and to finance NBFCs (especially the small and medium NBFCs) in a more constructive manner. We are confident that this step would go a long way to provide much needed long term liquidity support to NBFCs.
So, through these announcements RBI removed all the bottlenecks. They have allowed the banks to use this fund to lend to the NBFCs by term loans also. RBI has not prescribed any minimum credit rating. So the banks can now lend the underrated NBFCs also.
This has not been reported widely by media. These announcements have sent across a loud and clear message that RBI and the Ministry of Finance want banks to lend to NBFCs.